The Conversation
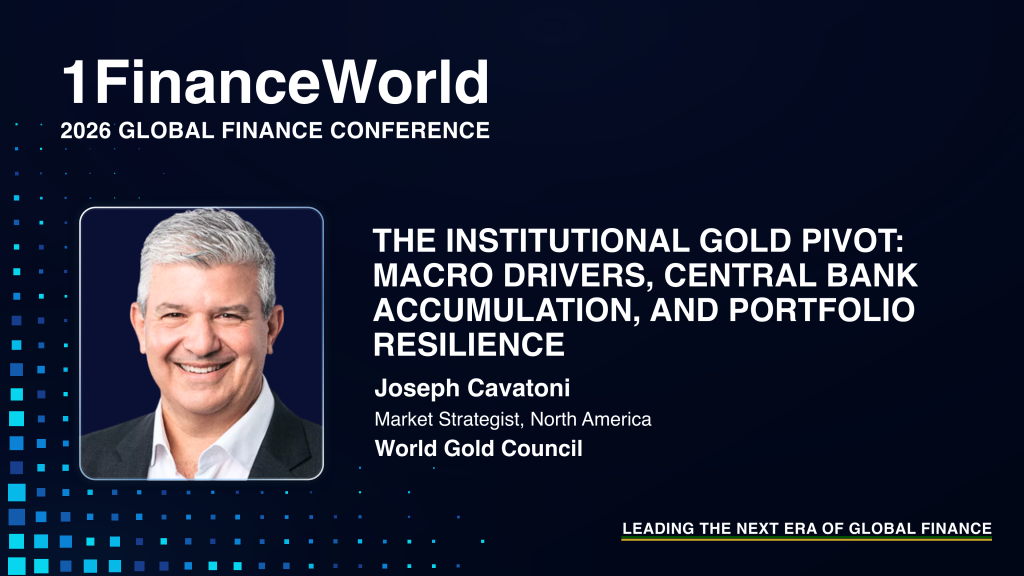
The Institutional Gold Pivot: Macro Drivers, Central Bank Accumulation, And Portfolio Resilience
Joseph Cavatoni in conversation with Henning Stein
An asset earns a place in a portfolio when decision makers can explain the job it is intended to perform and the evidence supporting that role. For institutional investors and wealth-management leaders, interest in gold becomes more useful when it leads to questions about exposures, liquidity and implementation. A persuasive macroeconomic narrative is one input. The allocation also needs a clear account of how the asset is held, how its market works and how it fits the objectives and constraints of the portfolio it joins.
Joseph Cavatoni of the World Gold Council develops that perspective in a 1FinanceWorld conversation with host Henning Stein. Their discussion brings together physical gold flows, sovereign financing concerns, central-bank reserve decisions and the infrastructure through which investors access the market. Cavatoni argues for understanding the purposes of different participants and the mechanics of different instruments. For leadership teams, that approach connects a broad investment thesis with the practical research and operational decisions needed to assess it responsibly.
Read Market Activity Through Its Economic Purpose
Cavatoni begins with the physical market. He describes the World Gold Council's work tracking where metal moves and how it is held across investment, jewelry, central-bank reserves and other uses. That underlying movement provides a basis for interpreting financial-market activity. His approach directs attention to who is acquiring or releasing an exposure and what their decisions may mean for demand. A useful market assessment therefore needs to distinguish changes in ownership from the activity that makes an existing holding easier to trade.
He illustrates the distinction through physically backed exchange-traded funds. Creating or redeeming interests in these funds affects the metal held behind them. Trading an existing fund interest between investors provides another form of market liquidity. The two activities can both matter, but they answer different questions. Treating exchange turnover as if every transaction represented an additional physical holding would confuse the market signal. Cavatoni's explanation gives allocators a more precise way to ask what a particular data point actually measures.
Futures serve another purpose in his account. Their maturity and rollover characteristics can support a participant seeking an exposure or a hedge over a defined period. That differs from choosing direct physical ownership or a particular fund structure. Cavatoni prefers language that explains these mechanisms rather than collapsing regulated financial instruments into a single dismissive label. His distinction encourages an examination of the product, its terms and the intended use, without assuming that every route into the gold market creates an identical ownership relationship.
For a research team, the editorial implication is to organize information around the decision it can inform. Cavatoni highlights a weekly markets monitor for recent developments and a quarterly demand report for the broader pattern of uses and flows. Combining those perspectives can help distinguish a short-term market response from a change in underlying demand. The discipline is to know what a report measures, what it leaves unresolved and how its evidence relates to the allocation under review, rather than treating a large quantity of data as understanding by itself.
Define The Portfolio Role Before The Allocation
Cavatoni connects the case for considering gold with concerns about sovereign debt, financing conditions and confidence in conventional portfolio diversifiers. These are his interpretation of the macroeconomic environment. He sees debt sustainability and the reliability of bonds as questions that deserve closer attention, alongside interest rates and inflation. The discussion presents a perspective for testing an investment thesis, rather than establishing that a particular debt level or policy action will produce a predetermined gold-price outcome.
The conversation also preserves tension within that thesis. Cavatoni acknowledges that monetary conditions can create near-term headwinds for gold, even when longer-term concerns support interest in it. He describes a market that can serve both investors building a core holding and participants expressing shorter-term views. Momentum and speculation can affect its behavior alongside reserve and investment demand. For an allocator, those distinctions matter because a structural case does not determine the path of returns or remove the possibility of volatility.
Liquidity is another part of his argument. He asks investors to consider the availability of capital when it is needed, including the constraints that can accompany allocations to private markets. Cavatoni sees a possible role for gold within that discussion, while explicitly recognizing that portfolios differ. Adding an asset also means changing the combination of exposures already held. The question is therefore about the contribution to a particular portfolio, rather than whether an attractive characteristic in isolation settles the size or suitability of an allocation.
Leadership can translate this reasoning into a stated purpose for each proposed holding. A review can ask whether the objective is diversification, liquidity, a long-term store of value or an expression of a market view. It can then examine the evidence for that role and the risks introduced by the way the exposure is implemented. Recording those choices makes future review more meaningful: a change in price, market conditions or operating needs can be assessed against the reason the allocation was established.
Central-Bank Decisions Reflect More Than One Motive
Cavatoni uses the World Gold Council's central-bank survey to explore the reasoning behind reserve decisions. He discusses diversification, inflation concerns, domestic economic conditions and the need to preserve liquidity. His account resists reducing those decisions to a single geopolitical message. The relevance of a reserve asset depends on the obligations, currency conditions and financial pressures a central bank is managing. Understanding those purposes provides a stronger basis for interpreting activity than assuming that every purchase expresses the same view.
He also distinguishes a gradual adjustment in reserve composition from an effort to displace the dollar outright. In his reading of the survey, central banks can seek less dependence on particular currencies while still operating within an existing financial system. They can buy gold, hold it or use and sell it as circumstances require. Buyers and sellers coexist. That qualification matters when an investment narrative portrays central-bank demand as one continuous movement in a single direction, with no room for changing domestic needs.
The leadership lesson is to investigate the motivation behind a reported flow before using it to support a forecast. A reserve manager, a wealth manager and a short-term trader may engage with the same market for different reasons. Their choices need not persist on the same schedule or respond to the same signal. Examining those differences can improve a team's understanding of demand while keeping the limits of its inference visible. A reported transaction is evidence of an action; its future implications still require analysis.
Match Access And Infrastructure To The Intended Use
Implementation becomes a central theme when Stein asks about owning gold through financial instruments or in physical form. Cavatoni describes both as possible routes, with different questions to resolve. For a physically backed fund, he emphasizes understanding its backing, the counterparties involved and the structure under which it operates. These are areas for examination, rather than a claim that a product label removes operational or financial risk. The chosen instrument has to fit the investor's intended use and the conditions under which it may be traded or redeemed.
Cost and market functionality also need to be considered together. Cavatoni distinguishes a holding intended to remain in place from an instrument used more actively for trading or other capital-markets purposes. A fee comparison can miss the reason different products offer different features. A leadership review can connect the expected pattern of use with liquidity, available functions and total implementation costs. That makes product selection an extension of the allocation decision, rather than a separate exercise based only on a headline price.
Direct physical ownership introduces a different operational agenda. Cavatoni discusses where and how metal is held, the premium paid to acquire it and the terms under which it could later be sold. Those questions bring custody and the exit process into view. A decision to hold a physical asset is incomplete without considering what happens after purchase. For decision makers, an explicit account of storage, trusted relationships and access to liquidity can make the difference between a stated portfolio role and a workable implementation.
His discussion of wholesale digital gold follows the same focus on practical use. Cavatoni describes an effort to improve how large market participants can mobilize physical holdings, use them as collateral and access trading. He distinguishes that operational objective from merely creating a token for speculative retail activity. The proposed value lies in addressing friction within the wholesale market. This is his account of an infrastructure initiative and its intended benefits, rather than a claim that the technical, regulatory or adoption questions have already been resolved.
For business leaders evaluating such an initiative, the useful test is the problem it is designed to solve. A new interface or digital representation should be assessed against settlement needs, trusted relationships and the responsibilities of the institutions involved. Technical and regulatory specialists can examine the implementation while commercial teams evaluate the demand and economics. Bringing those perspectives together helps distinguish a market improvement with a clear use case from an innovation narrative whose operating value remains uncertain.
Gold allocation gains discipline when purpose, evidence and implementation stay connected. Cavatoni's conversation encourages leaders to understand physical flows, examine the motives behind reserve decisions and choose access arrangements that fit the job an asset is expected to perform. That approach supports a more deliberate review of opportunity and risk without making uncertainty disappear. The leadership contribution is to ensure that a compelling investment idea can be explained, evaluated and operated with the same care, then reconsidered as needs and evidence change.
Continue The Conversation
The Institutional Gold Pivot: Macro Drivers, Central Bank Accumulation, And Portfolio Resilience
Joseph Cavatoni and Henning Stein
Watch The Full Conversation