The Conversation
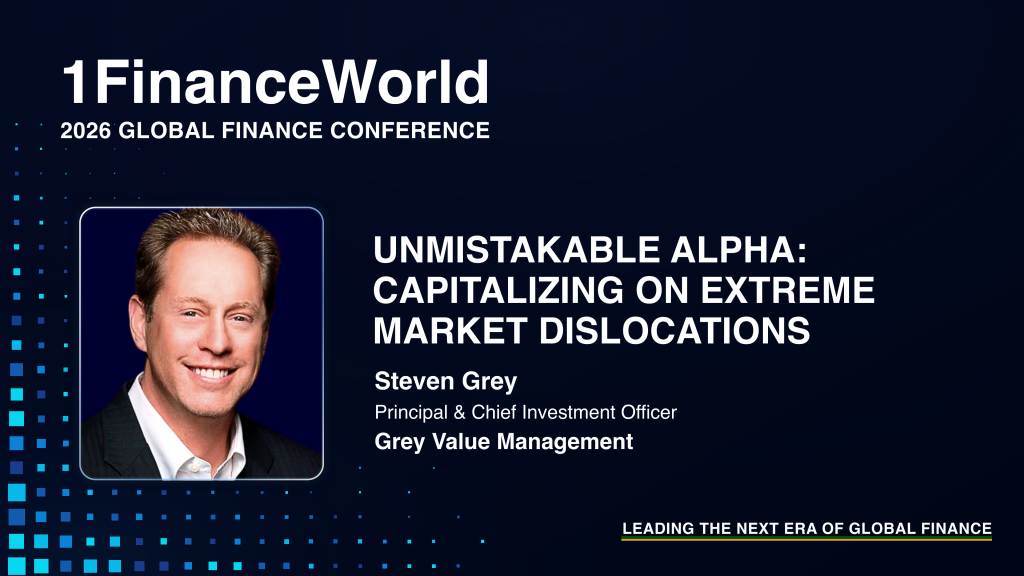
Unmistakable Alpha: Capitalizing On Extreme Market Dislocations
Steven Grey in conversation with Henning Stein
The ability to pursue opportunity during a market dislocation depends partly on the decisions made before it arrives. Financing commitments, business resilience and access to capital shape the choices available when conditions change. A promising investment story becomes more useful when leadership can explain the underlying economics and the risks being accepted. For business and investment leaders, that means building a process that can assess opportunity while preserving the capacity to respond to uncertainty.
Steven Grey of Grey Value Management develops that perspective in a 1FinanceWorld conversation with host Henning Stein. His discussion connects fundamental company research with the compensation investors receive for risk, the resilience of corporate balance sheets and the optionality of cash. He also examines the economics behind enthusiasm for artificial intelligence and the role he assigns to selected gold-mining investments. Across these subjects, his emphasis remains on understanding what an investment can deliver and the financial structure supporting it.
Start With The Business Behind The Narrative
Grey's approach begins with the work of examining companies. In the conversation, he describes reading filings and acknowledges the demanding routine that fundamental research can require. That starting point matters because it grounds an investment judgment in information about the business itself. The discussion moves from a broad market outlook toward the question of whether the economics supporting an investment have received sufficiently close attention.
He applies that question to AI. Grey argues that many investors would struggle to explain the industry's wider ecosystem, the different applications and the revenues or margins they expect particular companies to achieve. He also points to competition as a challenge to assumptions about sustained high profitability. His concern is the rigor of the investment case in an industry whose technology and competitive structure are evolving quickly. He recognizes that assessing the eventual distribution of profits is difficult.
For leadership, that suggests examining an innovation thesis at the level of a specific business model. A review can identify the customer need, the way revenue would be earned, the resources required to deliver the product and the assumptions supporting margins. It can also consider which advantages could persist as competitors respond. This gives the team a more assessable proposition than a general expectation that the whole industry will prosper.
The research process can make uncertainty visible. An investment committee can distinguish facts available in filings from management's expectations and the team's own judgments about the future. Recording those distinctions helps leaders recognize where a valuation depends on evidence and where it depends on a scenario. It also creates a basis for revisiting the decision as the business develops, rather than allowing confidence in a broad narrative to substitute for continued examination.
Evaluate Compensation For The Risk Taken
Grey describes a convergence of government indebtedness, fiscal pressures and monetary conditions across developed markets. In his assessment, these forces have increased investors' concern about the risk attached to sovereign debt. He looks across countries for the underlying pressures affecting securities rather than assuming that a different geography automatically provides a different economic situation. His account connects the macroeconomic environment with the terms on which investors are being asked to commit capital.
That reasoning informs his view of longer-dated bonds. Grey notes that his fund does not have a mandate requiring a fixed-income allocation. Within that flexibility, he sees the additional compensation available for extending maturity as insufficient for the additional risk. He also recognizes the importance of the depth and liquidity of the U.S. debt market to investors moving large sums. The conversation distinguishes an investment's practical usefulness from his judgment about the attractiveness of its underlying terms.
When considering government debt, Grey directs attention to the revenue available to service obligations. He questions whether a comparison with the size of an economy or its accumulated wealth answers the practical question of how interest will be paid. His argument emphasizes the relationship between financing commitments and the resources available to meet them. It is a perspective on financial capacity that he brings to the wider discussion of rising debt-servicing burdens.
For business leadership, the useful application is to make the financing question explicit. A review can examine the obligations being assumed, the cash flows supporting them and the duration of the commitment. It can then assess the compensation offered for accepting that exposure within the organization's own requirements. Keeping those elements together makes an allocation decision more precise and helps distinguish a necessary operational use of capital from an investment chosen for its expected return.
Look For Resilience In The Capital Structure
Grey identifies opportunities in Japanese equities through the characteristics of individual companies. He discusses businesses with resilient balance sheets and little or no material debt, alongside the ability of some companies to raise prices. In his account, limited debt obligations can strengthen a business's ability to withstand market shocks. The example brings attention to the actual capital structure behind an equity investment and the demands that financing places on the operating business.
He also challenges the assumption that adding leverage necessarily improves a company's financial profile. Grey describes the market's pressure for efficient use of capital, while emphasizing that more leverage can create more vulnerability. This makes capital efficiency and resilience questions to examine together. His assessment asks what a financing decision does to the company's ability to navigate difficult conditions, alongside what it does to the apparent efficiency of its balance sheet.
The same scrutiny extends across sectors. Grey describes himself as sector agnostic and says he looks first through the lens of the balance sheet when assessing resilience. He does not assume that a familiar defensive label settles the question, citing utilities in his discussion of businesses that can encounter financial difficulty. His approach directs research toward the company and its financial position rather than relying on the reputation of the category in which it operates.
A leadership team can use that approach to connect financial structure with the continuity of the business. It can examine the commitments that must be met through a downturn, the resources available to meet them and the investment the company still needs to make. That review gives resilience a more concrete meaning. It also helps explain why two businesses exposed to a similar market can offer their owners different capacities to endure disruption and pursue subsequent opportunities.
Preserve The Capacity To Act
Grey discusses gold-mining investments through the role he wants them to play. He describes looking for miners whose exposure to the gold price can be reflected in dividends and whose forward selling does not remove too much of that exposure. He uses an insurance analogy to explain the protective role he intends for positions selected on those terms. The discussion connects a broad asset view with the policies and financial behavior of the companies used to express it.
Cash has a distinct role in his process. At the time of the conversation, Grey sees short-term income as an attraction alongside the ability to keep capital available. He argues that investors underprice the optionality of cash. His assessment treats the capacity to make a future decision as part of what an allocation can contribute. It reflects a willingness to examine opportunity without assuming that every available commitment is attractive enough to warrant immediate investment.
For leadership, that suggests giving liquidity an explicit purpose in the allocation review. The team can identify the obligations it needs to support and the opportunities for which it wants to preserve capacity. It can also define the evidence and decision process that would justify deploying available capital. This makes flexibility something the organization can assess and manage, with responsibilities attached to it, rather than an undefined consequence of waiting.
Maintaining that capacity still requires active research. A team preparing for dislocations can investigate businesses, review financing structures and develop a clear account of the conditions under which an investment would become attractive. It can then update that work as information changes. Preparation gives patience a practical function: leaders have a basis for evaluating a new opportunity when it appears, rather than having to construct the entire investment case under the pressure of a market move.
Grey's conversation brings research, resilience and flexibility into the same decision process. A leadership team can examine the business behind a narrative, test whether the proposed terms compensate for risk and assess what an allocation contributes to its ability to act. The resulting discipline makes the reasons for committing capital clearer. It also preserves a basis for reconsideration, allowing leaders to pursue market opportunities with a considered account of the economics, obligations and evidence behind their decisions.
Continue The Conversation
Unmistakable Alpha: Capitalizing On Extreme Market Dislocations
Steven Grey and Henning Stein
Watch The Full Conversation