The Conversation
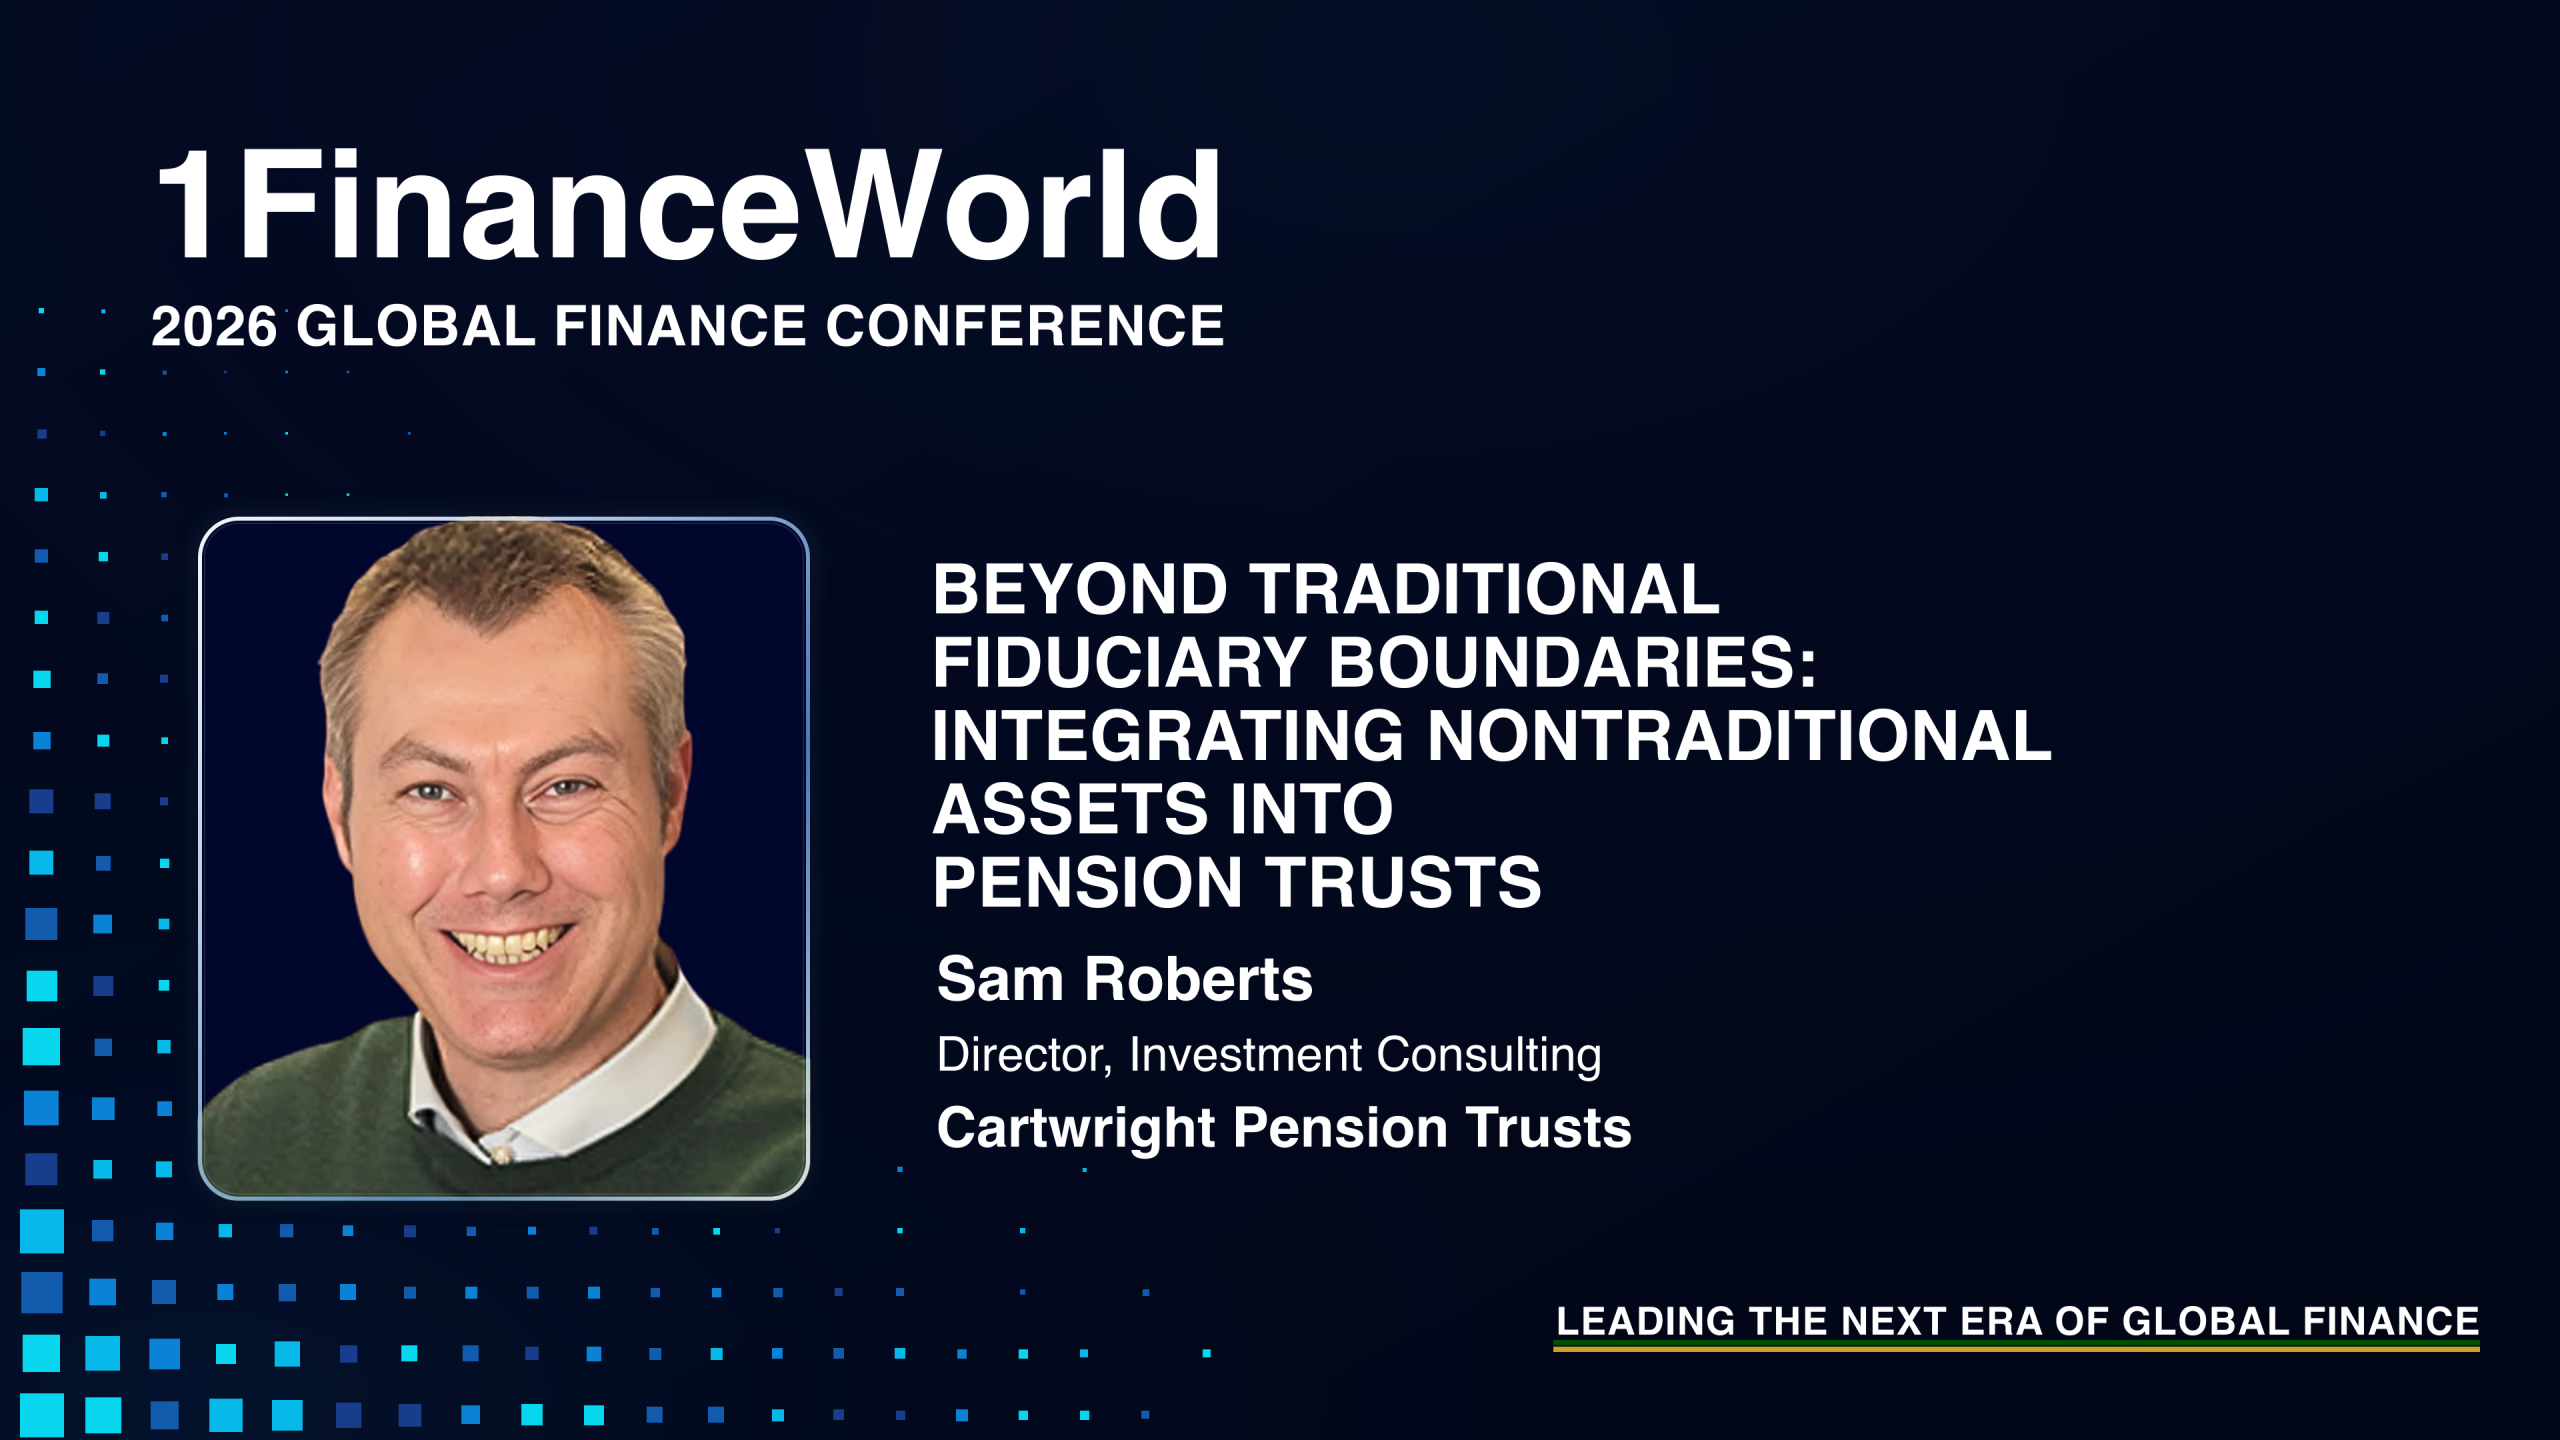
Beyond Traditional Fiduciary Boundaries: Integrating Nontraditional Assets Into Pension Trusts
Sam Roberts in conversation with Henning Stein
Innovation in pension investing begins with a demanding question: what does a new opportunity contribute to the obligations the scheme already carries? A novel asset or a more efficient market interface can attract attention, but trustees still need an account of objectives, risks and implementation. For pension and business leaders, the strength of a decision lies in connecting the investment idea with the particular institution that would hold it. That connection gives innovation a clearer purpose and makes its consequences more assessable.
Sam Roberts, Director of Investment Consulting at Cartwright Pension Trusts, explores that connection in a 1FinanceWorld conversation with host Henning Stein. Discussing his firm's work with a corporate defined-benefit pension scheme, he explains the process behind considering Bitcoin, choosing a custody arrangement and testing difficult outcomes. The conversation then moves into liquidity, liability management, portfolio concentration and AI-supported research. Across those subjects, Roberts keeps returning to the circumstances of the client and the governance required to make a particular decision responsibly.
Start With The Scheme’s Objectives And Horizon
Roberts establishes an important boundary at the beginning: he is describing advice developed for one scheme within its own decision framework. He does not present the resulting allocation as a prescription for other institutions. The first conversation was about whether an asset deserved consideration in light of that client's objectives. That starting point distinguishes a research opportunity from a recommendation and gives trustees room to examine a proposal before committing to it.
Time horizon is central to his explanation. Roberts contrasts a scheme approaching its liabilities more closely with one able to evaluate an investment over a longer period. Those different circumstances change the risks trustees may be willing or able to accept. The asset cannot be judged independently of the obligations it is intended to support. His account therefore resists treating the label of pension investor as evidence that all pension schemes should follow the same allocation approach.
He describes evaluating Bitcoin through the same broad questions used for other asset classes: its characteristics, risk and return, and potential role in the overall portfolio. The discussion of gold and Bitcoin also brings counterparty exposure and confidence in supply into view. Roberts distinguishes the physical basis of confidence in gold from the protocol and network questions involved in Bitcoin. These are elements of his investment reasoning, rather than a claim that the two assets are equivalent or that either removes every risk.
The leadership implication is to identify the institution's requirements before allowing an asset narrative to define the research agenda. A review can state what the scheme needs to achieve, which risks it already carries and the period over which a proposed exposure would be assessed. It can then examine whether the new idea helps address those needs. Keeping that sequence visible makes the decision more specific and creates a record of why the proposal was considered in the first place.
Treat Implementation As An Investment Decision
Roberts separates several stages of the allocation process. The first is whether to consider the asset at all; another is how much exposure would fit the particular investor's portfolio; a further stage is how to hold it. In the scheme he describes, the team examined direct Bitcoin ownership through an institutional custodian with segregated accounts and other protections. He presents that choice as an outcome of the client's objectives and attention to counterparty exposure, rather than a universally preferred ownership structure.
The distinction prevents implementation from becoming an afterthought. A long-term exposure still depends on the relationships, controls and practical arrangements through which it is held. Roberts contrasts an institutional custody process with the impractical image of trustees informally retaining access credentials themselves. His explanation connects the investment decision with operational responsibilities. A leadership team can examine who holds the asset, which parties are involved and how the arrangement supports the institution's requirements without assuming that any structure is free of risk.
His approach to tokenization follows a similar separation of questions. Roberts distinguishes the underlying asset from the infrastructure used to record ownership and support transactions. He sees potential operational improvements, while noting that institutions already have systems and relationships that often work well for their needs. A digital representation does not by itself change the economic exposure or establish a reason to replace an existing arrangement. Its value depends on a practical improvement that participants have a reason to adopt.
For leaders evaluating financial innovation, the useful test is therefore the work it improves. An initiative can be examined for benefits in trading, administration or access, alongside the effort required to change established operations. Commercial, investment and technical teams may need to answer different parts of that question. Keeping those responsibilities connected helps a decision maker assess the proposed improvement without confusing more sophisticated infrastructure with a stronger underlying investment case.
Test Resilience Across Liabilities And Scenarios
The discussion of the UK gilt-market crisis brings liquidity into that framework. Roberts distinguishes the principle of matching liabilities from the difficulty some schemes experienced supplying collateral quickly enough within leveraged arrangements. In his account, the operational capacity to meet a demand for collateral is a separate question from the rationale for managing a liability exposure. The example directs attention to the movement and availability of assets under pressure, rather than assuming that a sound strategic purpose establishes a workable response to every market condition.
He takes the same client-specific approach to uncertainty about sovereign debt, inflation and bond yields. Roberts asks whether a risk is one the scheme needs or wants to accept, including whether it can choose to hedge that exposure. He also distinguishes an abstract asset-allocation model from a portfolio designed around actual liabilities. A broad market view may help frame the questions, but it does not settle which combination of investments is appropriate for a particular institution or how its decisions should be made.
Scenario analysis gives those questions a more concrete test. Roberts describes explicitly examining an outcome in which the scheme's Bitcoin investment immediately lost all its value and never recovered. His account focuses on the effect on the scheme's overall objectives and whether that effect remained manageable for this particular client. The exercise is significant because it challenges the allocation with an adverse outcome, rather than assessing only a favorable long-term thesis. It does not establish that the same exposure would be tolerable in another scheme.
For leadership, the practical application is to connect a scenario with obligations and the capacity to respond. A review can examine the consequences for funding objectives, liquidity and the resources available when conditions deteriorate. It can also make clear which assumptions support a judgment that the institution can withstand an outcome. This gives an investment discussion a more considered basis: the team understands why it is accepting a risk and how that decision relates to the commitments it needs to maintain.
Connect Technology With Evidence And Oversight
Portfolio concentration provides another example of looking beyond an individual allocation. Roberts describes examining the exposure to technology and AI within equity indices alongside the rest of a client's investments. A concern within one part of the portfolio may be balanced or compounded elsewhere. Changing an index also changes other sector and geographic exposures. His discussion treats the decision to respond as something to evaluate after understanding the actual concentration, rather than assuming that recognizing a risk determines the next action.
He extends the assessment to the sponsoring employer. In a hypothetical example, a pension scheme whose employer depends on technology and AI could also hold a substantial investment exposure to the same businesses or theme. That combination deserves additional thought because the sources of support and investment performance may be sensitive to related conditions. The editorial implication is to examine the institution's wider dependencies, rather than limiting the review to the holdings shown in an investment report.
AI can assist that research, but Roberts emphasizes human oversight. He describes using tools to support analysis of concentration and underlying businesses while maintaining responsibility for the resulting portfolio decision. Stein also distinguishes applications used to organize and analyze information from the wider range of technology used in investment processes. The useful leadership question is which task the tool supports and what evidence the decision maker still needs to inspect, rather than treating the presence of AI as a complete description of a process.
Roberts's account of questioning AI-generated answers makes the verification task explicit. He describes seeing implausible financial data in an output and recognizes the risk of accepting a result too readily. For a research team, a fluent answer or an attractive chart should prompt examination of the underlying sources and assumptions. A process can make responsibility for that check clear before analysis informs an allocation. Technology adds more value when it helps the team investigate evidence and understand exposures than when its output bypasses the scrutiny applied to other research.
Pension governance connects innovation with the obligations that give investment decisions their purpose. Roberts's conversation brings objectives, horizon, implementation and adverse scenarios into one accountable process. It also shows why portfolio analysis needs to consider the institution around the assets and why better tools still require thoughtful review. For leaders, the enduring advantage is a decision that can be explained in relation to the scheme's needs, challenged against difficult outcomes and reconsidered as the evidence develops, with responsibility remaining clear throughout.
Continue The Conversation
Beyond Traditional Fiduciary Boundaries: Integrating Nontraditional Assets Into Pension Trusts
Sam Roberts and Henning Stein
Watch The Full Conversation